Expense IQ Money Manager

Screenshots
Details
- Rating
- 2.81K reviews
- Version
- 2.3.2
- Developer
- Handy Apps
Analysis by Norviv
Managing money is rarely difficult because people cannot understand the idea of a budget. The real problem is remembering small purchases, checking upcoming bills, and finding a system that remains usable when life is busy. I spent time with Expense IQ Money Manager as a personal finance app from Handy Apps, and I found its strongest quality in the way it brings everyday tracking, planning, and reminders into one place. It is not a flashy banking replacement, but it can be a practical notebook for people who want a clearer view of their spending.
My experience was also shaped by how comfortably different people can use it. A finance app needs to work not only at a desk with plenty of time, but also during a noisy commute, after a long day, or for someone who finds dense screens and repeated tapping tiring. Expense IQ makes several of those situations manageable, although it is not equally comfortable for every user. The interface feels more useful when you approach it with a simple routine rather than expecting it to automate every financial decision.
How Expense IQ handles everyday money management
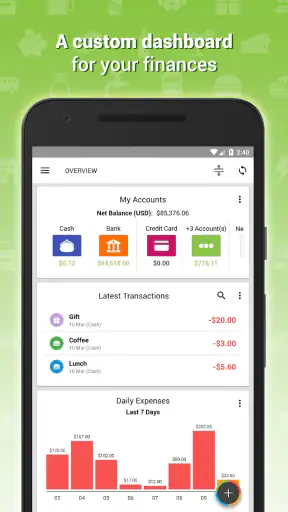
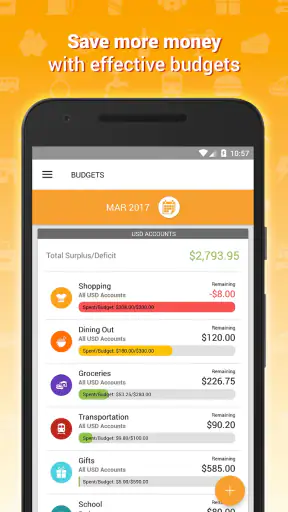
The app combines an expense tracker, budget planning tools, and bill reminders instead of separating those jobs across several applications. That combination matters because a spending record is much more useful when it can be compared with a plan and connected to a future payment. I could imagine using it for groceries, transport, subscriptions, household costs, and irregular purchases without needing a separate note-taking app for each category.
Expense IQ is free to install, while in-app purchases range from around three dollars to over one hundred dollars per item. That makes it sensible to explore the basic workflow before paying for anything. I would not treat the purchase options as a reason to commit immediately; the important question is whether entering transactions and reviewing the resulting information fits your habits. A beautifully organized budget is not helpful if logging each purchase feels like work you will avoid.
The app is rated for Everyone, which makes its subject matter broadly approachable, and it runs on Android starting with version 4.4. Handy Apps has kept the current release at version 2.3.2. Its reach is considerable, with over one million installs, although the average rating sits at 3.2 from around twenty-three thousand ratings. I read that combination as a useful warning to test the experience personally rather than assuming popularity means universal satisfaction.
Readability and navigation in real use
The clearest way to use Expense IQ is to give each transaction enough context at the moment you record it. Entering “lunch” is less useful than choosing the appropriate category and noting whether it was a one-off purchase or part of a recurring pattern. The extra few seconds can make later reviews much more meaningful, especially when you are trying to understand why a budget was exceeded.
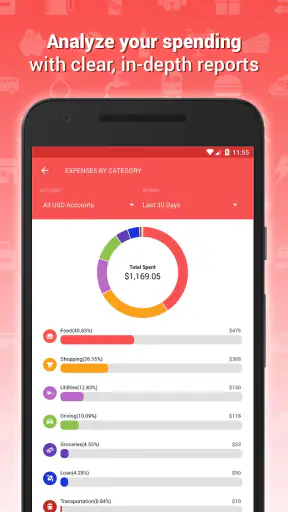
I found the app most approachable when I treated the main money view as a starting point, not as a complete financial explanation. A total can tell you that spending changed, but the category breakdown is what helps you decide what to do next. If the screen feels busy, I recommend reviewing one category at a time: food, transport, household bills, or discretionary purchases. That reduces the mental load and makes the app less intimidating for someone who is new to budgeting.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Readability is also affected by the type of information being displayed. Numbers, dates, categories, and reminders compete for attention, so users who prefer very minimal interfaces may need a few sessions to learn where everything belongs. I would begin with only essential categories and add detail gradually. Creating a long list of highly specific categories on the first day can make the tracker feel precise, but it often makes daily entry slower and harder to maintain.
One useful workflow is a short evening check rather than constant monitoring. I would record purchases during the day when convenient, then spend a few minutes checking uncategorized or questionable entries at night. This separates quick capture from careful review. It is especially helpful for people who become overwhelmed when they have to make every budgeting decision while standing in a shop or rushing between appointments.
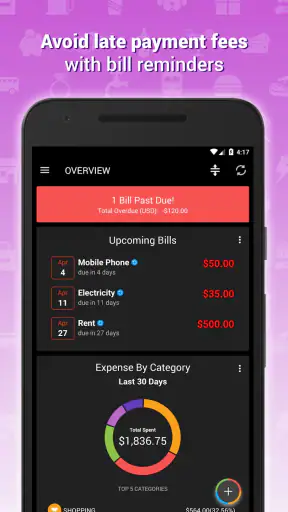
The bill reminder side can also support a more visual routine. Instead of waiting for a payment to surprise you, enter regular obligations early in the month and look at the upcoming list before making larger discretionary purchases. This does not replace checking your bank account, but it creates a second memory aid. For anyone who struggles with time awareness or remembering dates, that separation between “money spent” and “money already committed” is one of the app’s more valuable ideas.
Motor and sensory considerations
Money tracking involves repeated small actions, so physical effort matters more than it might seem. Adding a transaction can require several choices, and users with limited dexterity, tremors, joint pain, or fatigue may find repeated tapping inconvenient. I would reduce that friction by keeping categories broad and predictable. A short list means fewer movements and fewer chances of selecting the wrong item.
People who use a device with larger text, magnification, or other system-level display adjustments should try the complete entry process rather than judging the app from its opening screen. A financial interface can remain technically visible while still becoming awkward when labels wrap, controls move, or several values appear close together. Expense IQ may be workable in those setups, but comfort will depend on the phone, display settings, and the user’s tolerance for dense information.
For users with visual processing difficulties, a consistent naming system can make the app easier to scan. I would avoid near-duplicate categories such as “eating out,” “restaurants,” and “takeaway” unless there is a strong reason to separate them. Similar labels create extra decisions and make reports harder to interpret. One of my practical recommendations is to choose categories based on decisions you actually want to make later, not on every possible type of purchase.
Auditory access is a different matter. A person who cannot rely on visual reminders should not assume that a finance app alone will provide a complete alert system. I would pair the bill-planning habit with the device’s own calendar or reminder tools when a payment is especially important. That creates a more dependable backup without pretending that one app can cover every sensory preference.
Users who are sensitive to visual clutter may benefit from opening the app with a specific task in mind. “Check this week’s food spending” is easier to manage than “inspect everything.” Likewise, someone with attention difficulties may find it better to record a purchase immediately and postpone analysis until a calmer moment. The app supports a structured approach, but it does not remove the need to choose a manageable amount of information.
Situational access beyond the ideal setup
A realistic example is a parent buying groceries while managing a child, a shopping list, and a limited budget. In that situation, detailed entry at the checkout is unrealistic. I would record a quick transaction with the closest category, then correct or refine it later at home. The important trade-off is speed versus accuracy: a rough entry made immediately is usually more useful than a perfect entry that is forgotten.
The same approach works for shift workers, commuters, and anyone whose schedule changes frequently. A budget review does not need to happen at a fixed hour, but it does need a reliable trigger. Linking it to an existing habit, such as finishing a weekly grocery trip or preparing for payday, makes the app easier to sustain than relying on motivation alone.
Expense IQ can also be useful for someone who shares household responsibilities but does not want a complicated financial system. One person could use it to track recurring household costs while another handles day-to-day purchases. However, I would be cautious about treating it as a complete shared-finance solution without first agreeing on categories and entry rules. If two people record similar expenses differently, the reports can become confusing even when every individual transaction is correct.
Travel is another situation where the app may help but requires discipline. Spending in unfamiliar places is easy to misclassify, and exchange-rate assumptions can make a record less useful if you do not enter information consistently. I would use broad categories and add a short note identifying the trip or purpose. That preserves a useful memory of the expense without turning every transaction into a lengthy form.
For people with irregular income, a fixed monthly budget can be misleading. I would use the planning side as a cautious guide rather than a promise that the same amount will be available every month. Prioritize bills and essential categories first, then treat flexible spending as a range. The app can organize the information, but it cannot predict an unpredictable paycheck or decide which obligation should take priority.
Where the app still creates friction
The biggest limitation is that organization depends on user input. Expense IQ can make records easier to review, but it does not remove the ongoing responsibility of entering purchases accurately. Anyone looking for automatic bank synchronization, a hands-off financial dashboard, or investment analysis may find a dedicated banking or finance service more suitable. This app makes more sense for people who want control over the record rather than complete automation.
There is also a learning curve in deciding how much detail is worthwhile. Too little information produces vague reports, while too much creates an exhausting routine. I think the best compromise is to start with the categories that affect real decisions, then add another only when an existing category hides a meaningful pattern. That approach is less impressive on the first day, but much more sustainable after several weeks.
The average rating of 3.2 suggests that the experience does not satisfy everyone, and I can understand why a user might find the interface less immediate than a simple notes app. A note is faster for a single expense, while Expense IQ becomes valuable through accumulated structure. If you only need to remember one payment occasionally, this may feel like unnecessary effort. If you want comparisons, reminders, and a repeatable budget routine, the structure earns its place.
The in-app purchase range also deserves attention before making a decision. Since the app is free to start, I would first test whether the core process feels comfortable on your device and with your preferred accessibility settings. Do not pay simply because you have already entered several transactions. The right purchase is one that removes a genuine limitation for your workflow, not one that compensates for a routine you do not enjoy using.
Privacy-minded users should also adopt a sensible habit: record only the information needed to understand the transaction. Avoid turning notes into a detailed diary of personal circumstances. A category, amount, and brief purpose are usually enough for budgeting. This keeps the record useful and reduces the amount of sensitive context stored in the app itself.
Who should choose it, and who should look elsewhere
I would recommend Expense IQ to someone who wants a dedicated Android money journal with more structure than a spreadsheet or notes app. It is particularly suitable for users who prefer manual control, want bill reminders alongside spending records, and are willing to spend a few minutes maintaining categories. It can also suit beginners who need a concrete way to see where money goes without immediately adopting a complex financial platform.
I would be less enthusiastic for someone who needs strong automation, effortless shared accounts, or a very sparse interface. A person with significant motor fatigue may also want to test the full transaction flow before committing, because repeated manual entry can become the main barrier. Likewise, anyone who depends on nonvisual reminders should combine the app with device-level tools instead of relying on it as the only prompt.
Compared with a spreadsheet, Expense IQ is more convenient for repeated phone entry and more naturally focused on daily spending. A spreadsheet offers greater freedom for custom formulas and unusual household arrangements, but it can be cumbersome on a small screen. Compared with a banking app, Expense IQ is better suited to intentional categorization and personal budgeting, while a bank’s own application is usually the place to verify balances and transactions. I would use those tools together rather than expecting one to replace the other.
Compared with a simple notes app, the advantage is the ability to turn individual entries into a broader spending routine. The cost is more setup and more decisions. That trade-off is central: Expense IQ rewards consistency, whereas a notes app rewards speed. Neither is automatically better; the right choice depends on whether you need a searchable financial structure or only a quick memory aid.
My inclusive verdict after using the money manager
Expense IQ Money Manager is a practical finance app with a clear purpose: help people record spending, plan budgets, and remember bills in one organized space. I appreciate that it can support a calm review routine instead of forcing every financial decision to happen immediately. Its most inclusive quality is not a special claim or certification, but the flexibility to use broad categories, review information in smaller pieces, and adapt the routine to busy or tiring days.
At the same time, accessibility here depends heavily on personal setup and habits. The app cannot make dense financial information effortless for everyone, and manual entry may be tiring for users with motor or attention-related challenges. A larger display, system accessibility settings, external reminders, and a carefully limited category list can make the experience more manageable, but those adjustments require planning.
My advice is to begin with one week of essential tracking: income, recurring bills, groceries, transport, and one flexible category. Test whether you can enter purchases comfortably, understand the summaries, and remember to check upcoming obligations. If that small routine helps you make better decisions, expanding it gradually is worthwhile. If it already feels burdensome, a simpler note-based method or a more automated financial service may be kinder to your time and energy.
Overall, I see Expense IQ as a useful companion for deliberate money management rather than a universal financial solution. It is free to begin, widely used, and broad enough for everyday budgeting, but its value comes from the quality of the routine you build around it. For me, the deciding factor is not how many features appear on the screen, but whether the app makes your next money decision clearer.
Frequently Asked Questions
01What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you track spending, organize income and expenses, manage budgets, and monitor your overall financial habits. After reviewing its main tools, the app feels most useful for users who want a clearer picture of where their money goes without relying on spreadsheets. It can also help you follow recurring bills, savings goals, and account balances in one place.
02Does Expense IQ Money Manager support multiple accounts and currencies?
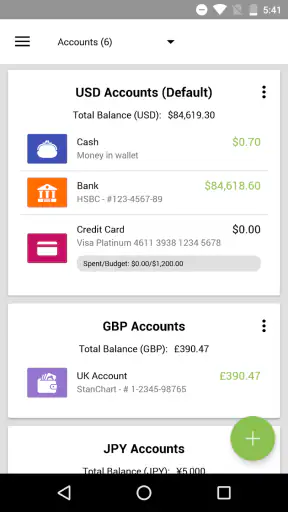
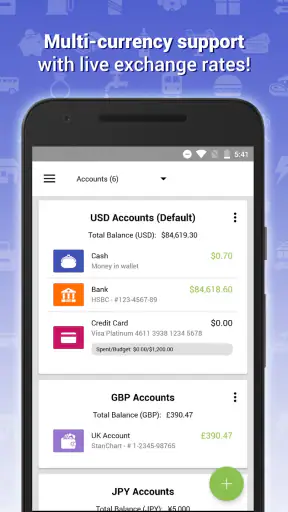
The app is built to manage more than one financial account, allowing you to separate cash, bank accounts, credit cards, savings, or other personal funds. This makes it practical for users with several sources of money. Currency availability and conversion behavior can depend on the app version and device settings, so users who regularly handle international accounts should check the current store description before downloading.
03Is Expense IQ Money Manager free to download and use?
Expense IQ Money Manager may be available as a free download, but some advanced features can require an upgrade or paid version, depending on the platform and release. Before installing, review the Google Play Store or Apple App Store listing for current pricing, subscriptions, advertisements, and in-app purchase details. The free tools may be enough for basic expense tracking, while premium functions are generally aimed at more demanding budgeting needs.
04Can I use Expense IQ Money Manager to create budgets and track bills?
Yes, budgeting and bill monitoring are among the app’s most useful functions. You can assign spending to categories, set limits, and review whether your actual expenses are staying within your planned budget. Recurring transactions and reminders can also make it easier to remember regular payments. However, the app is primarily a personal tracking tool, so automatic bill payment or direct banking services should not be assumed unless explicitly listed in the current version.
05Is my financial information safe in Expense IQ Money Manager?
Because Expense IQ Money Manager stores sensitive information such as transaction records, account details, and spending patterns, privacy should be considered before entering data. Use a strong device lock and enable any available app security features, such as a PIN or biometric protection. Also read the developer’s current privacy policy to understand data collection, backups, synchronization, and third-party sharing. Avoid entering online banking passwords unless the app specifically and securely supports that feature.


